A water damage insurance claim goes more smoothly when you do a few things in the right order. The first is safety, the second is stopping more damage and the third is documentation. We are not an insurer or an adjuster, and this guide is general, so your policy comes first.
Here are the steps most Decatur homeowners follow, with what to keep and what to ask.
Step 1: Make it safe and stop the water
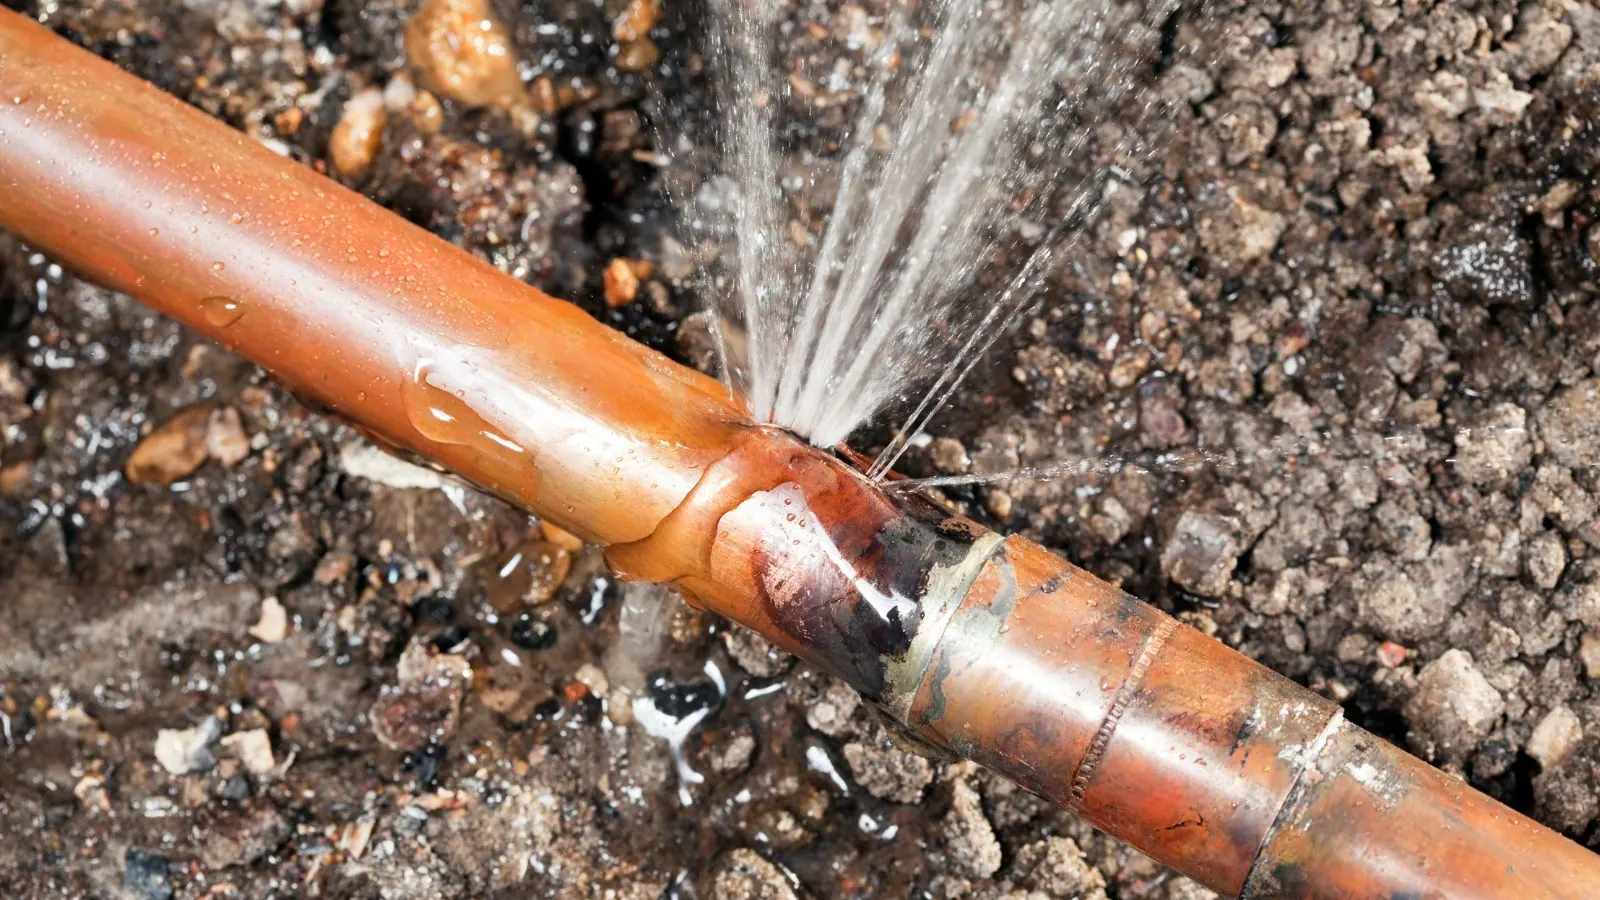
Close the shut-off valve on a leaking line, or the main valve. Turn off power to wet areas only if you can reach the panel dry. Keep people and pets out of contaminated water, which includes sewage and flood water.
Stopping the water is also part of your duty under many policies to protect the property from further damage. Keep the receipts for anything you buy to do so.
Step 2: Photograph and video before you clean
Take wide shots of each affected room, then close-ups of the damage, the source and any labels on appliances. Video that pans the room can help. Include the date and, where possible, a view of what failed.
Do not throw away damaged materials until your adjuster agrees. If something must go for safety, photograph it first.
Step 3: Report the loss promptly
The Alabama Department of Insurance notes that policies may require notice within a set time frame and that most insurers have reporting deadlines. Call your insurer or agent as soon as it is safe, and ask for the claim number and the adjuster contact.
Write down who you spoke with, the date and what they told you. If you are unsure how to reach your insurer, the department can help locate contact information.
Step 4: Dry and mitigate
Water damage gets worse with time. Extraction and drying are time-sensitive, and policies often expect them. We work with moisture readings, and we log them each visit so the drying is documented. See water extraction and structural drying for what each stage does.
Ask your adjuster whether they want to see the damage before demolition. If they cannot come quickly, photographs and moisture logs help.
Step 5: Keep a record
| Item to keep | Why |
|---|---|
| Photos and video | Show the damage before cleanup |
| Plumber or repair invoices | Show the cause and cost |
| Drying logs and moisture readings | Show the work was needed |
| Receipts for emergency purchases | Support reimbursement |
| Claim number and contact notes | Keep the process on track |
| Damaged items list with values | Support the contents claim |
Step 6: Beware of pressure and fraud
The department advises getting multiple contractor bids, asking for references and verifying licenses, permits, insurance and bonding. Be cautious of anyone who asks for a large payment up front or pushes you to sign over your claim.
You choose your contractor. Ask for a written scope before work begins.
Working with the adjuster
An adjuster inspects the loss, reviews the policy and estimates the covered amount. Their estimate and a contractor scope may differ. That is normal, and it is the reason documentation matters.
If the numbers differ, ask the adjuster what they excluded and why. A moisture log and photos taken before demolition can resolve many gaps. Keep every message in writing where you can, and note the date of each call.
Mitigation versus repair on a claim
A claim often has two phases. Mitigation is the emergency work, such as extraction, removal of wet materials and drying. Repair is the rebuild. They may be billed separately and reviewed separately.
Ask your insurer how each is handled. Some insurers want a say before drywall is rebuilt, and some want to see the drying logs first. Do not close up walls until you know. See ceiling water damage repair for an example of a repair that follows drying.
Living through the repair
Large losses can make a home hard to live in. Some policies include additional living expense coverage for that period. Ask whether yours does, what it covers and what proof is needed.
Keep receipts for hotels, meals above normal cost and storage. Write down dates, since coverage usually runs for a limited period.
Common mistakes to avoid
- Throwing away damaged items before photographing them.
- Waiting days to report the loss.
- Signing a contract or assignment of benefits without reading it.
- Closing walls before moisture readings are normal.
- Accepting a verbal scope with no written detail.
- Skipping the contents list.
What Decatur homeowners should know
If your loss involves a repair that needs a permit, ask the City of Decatur Building Department, since its page lists repairs and remodeling of existing structures among the work that needs one. Permits and receipts become part of your records.
For storm-related claims, keep dated weather information. The National Weather Service office in Huntsville serves north Alabama. If you live in Mooresville or Somerville, local permit authorities differ, so ask which one applies.
Decatur questions answered
How soon should I report a water damage claim?
As soon as it is safe. The Alabama Department of Insurance notes that policies may have notice requirements and that most insurers have reporting deadlines.
Should I start cleanup before the adjuster arrives?
Stop the water and protect the property. Photograph first, and ask your adjuster before throwing anything away. Drying is time-sensitive.
Do I have to use the contractor my insurer suggests?
Generally you choose. Get bids, ask for references and verify credentials as the Alabama Department of Insurance suggests.
What if my insurer denies the claim?
Ask for the reason in writing and review your policy. The Alabama Department of Insurance can answer questions about consumer rights.
Who can help me find my insurer's contact information in Alabama?
The Alabama Department of Insurance can help locate a company's contact information, according to its consumer guidance.